Risk is often sold as a math problem. If you hedge correctly, the numbers should cancel each other out. But in the world of crypto infrastructure, math is rarely the problem. The plumbing is. Right now, a growing number of crypto-focused hedge funds are staring down a liquidation trap that has nothing to do with being wrong about the market and everything to do with where their dollars are parked.
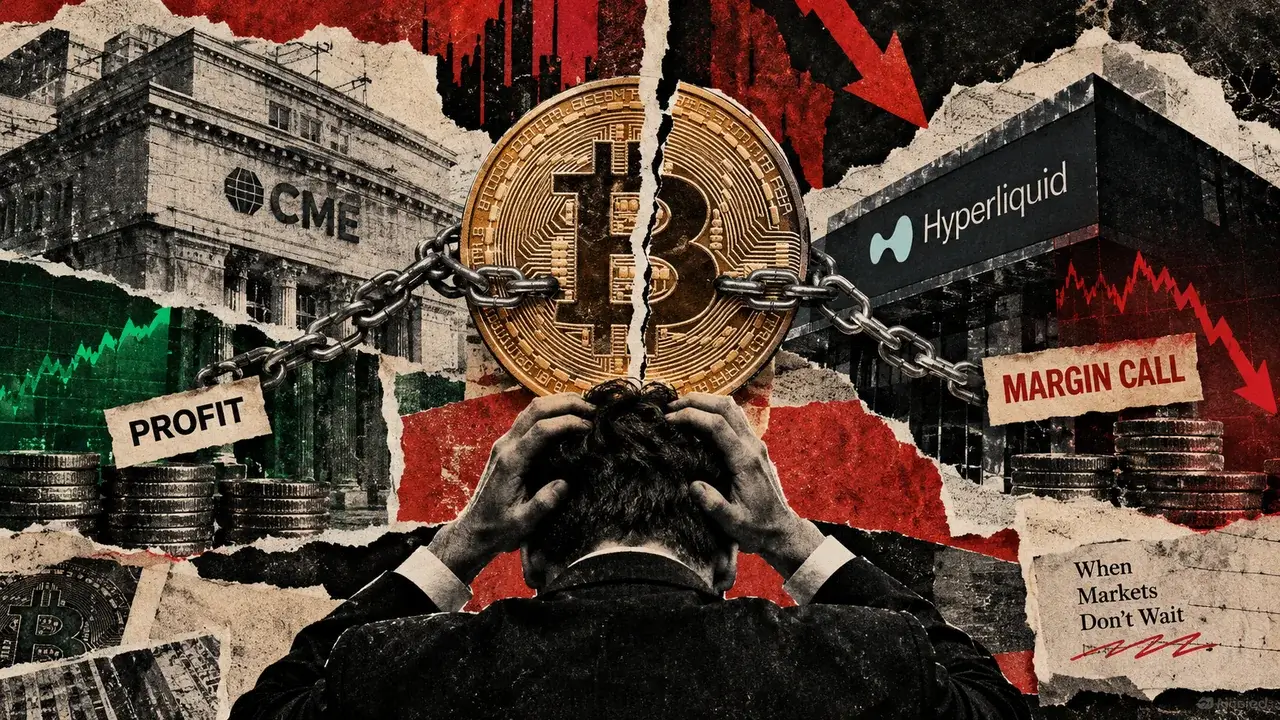
We are seeing a massive disconnect between institutional venues like the CME and decentralized or offshore platforms like Hyperliquid. On paper, a fund might be perfectly delta-neutral. In practice, they are one volatility spike away from a margin call that destroys their business because their collateral is trapped in silos that don't talk to each other.
The Illusion of the Perfect Hedge
The trade itself is simple. A fund goes long on a spot asset or a perp on a high-leverage exchange like Hyperliquid, then shorts the equivalent amount on the CME to capture the basis. If the price goes up, the short loses and the long wins. If the price goes down, the short wins and the long loses. The fund collects the funding rate or the spread, and everyone goes home happy.
Except the market doesn't move in a straight line, and exchanges don't share wallets. When Bitcoin takes a sudden 10% dive, that short position on the CME starts printing money. That is great for the fund's balance sheet, but it does nothing for the long position on the other exchange that is currently bleeding collateral. The exchange where the long is held doesn't care that you have millions in profit sitting in a bank account or a regulated clearinghouse. They only care about the collateral in their engine.
The Liquidation Gap
This is where the trap snaps shut. To keep the losing side of the trade from getting liquidated, the fund needs to move their profits from the winning side over to the losing side. In a traditional market, a prime broker might handle this cross-margining. In crypto, you are your own prime broker, and the roads are full of potholes.
Moving capital from a regulated entity like the CME back to a crypto-native platform isn't instantaneous. You have banking hours, compliance checks, and blockchain confirmation times. If the market moves fast enough, the fund gets liquidated on their long position before their wire transfer even hits the desk. They are left with a naked short on the CME, and suddenly, they aren't hedged anymore. They are just gambling on a crash.
Why Builders Should Care
For those of us building in this space, this isn't just a story about hedge funds losing money. It is a massive flashing sign pointing to a lack of mature infrastructure. We talk a lot about decentralization, but we don't talk enough about capital efficiency across disparate systems.
If you are building a DeFi protocol or a centralized exchange, your biggest competitor isn't another app; it is the friction of moving money. The current state of the market forces users to over-collateralize every single leg of a trade just to survive a temporary wick. That is dead capital that could be used for building, lending, or innovation.
- Interoperability is a risk management tool. We need better bridges between legacy finance and the crypto ecosystem that don't rely on three-day settlement windows.
- Settlement layers are the bottleneck. The speed of a trade doesn't matter if the speed of the collateral move is slow.
- Cross-margin solutions are the holy grail. Any platform that can safely allow for cross-exchange margining is going to win the institutional war.
The Founder's Perspective
From where I sit, this looks like the growing pains of a market trying to grow up too fast. Founders often focus on the flashy side of crypto—the high-yield, the fast execution, the UI. But the real money is made and lost in the back office. The hedge funds currently getting squeezed are victims of their own complexity. They assumed the market was more integrated than it actually is.
If you are a founder in the AI or crypto space, take a look at your own dependencies. How many of your systems rely on a third party to be fast, only for that third party to be bottlenecked by a legacy process? Whether it is API rate limits or banking rails, the "liquidation trap" is a metaphor for any system where the inputs move faster than the safety nets.
The biggest risk in crypto isn't being wrong about the price; it is being right about the price but wrong about the plumbing.
Practical Realities for the Next Cycle
We are going to see more of these blow-ups. As Bitcoin enters its next phase of institutional adoption, more funds will try to play the basis trade. They will see the 10% or 15% annualized returns and think it is free money. They will forget that volatility is a feature, not a bug.
For builders, the opportunity is clear: solve the fragmentation. Whether that is through institutional-grade DeFi hooks or better custody solutions that allow for real-time collateral movement, the market is desperate for a way to stop this bleed. Until then, stay skeptical of anyone claiming a "risk-free" hedge. In this market, the only thing that is risk-free is holding your own keys and knowing exactly where your collateral is at 3:00 AM on a Sunday.
A Final Reality Check
The lesson here is simple: math only works when the environment allows it to. You can have the most sophisticated algorithmic hedge in the world, but if your exchange requires a manual wire transfer to keep your margin alive during a flash crash, you aren't a trader—you're a passenger. Builders need to stop obsessing over the trade and start fixing the pipes. That is where the real value is going to be created over the next five years.
Read the original at CryptoSlate →