The Plumbing is Finally Changing
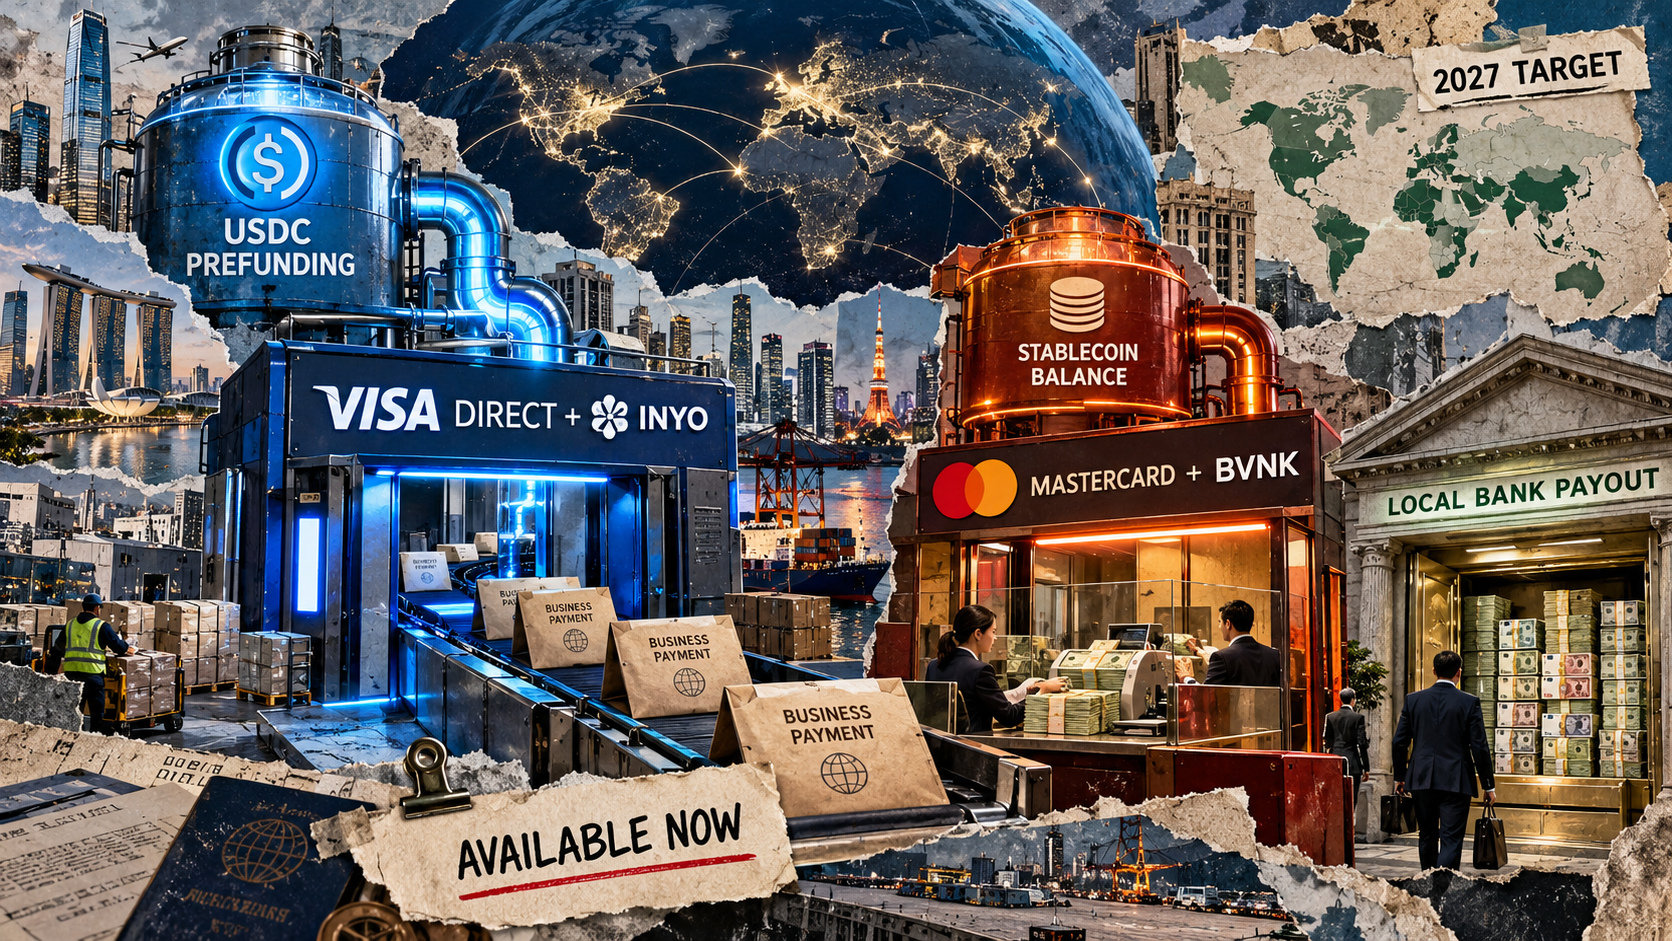
For years, the promise of crypto for builders wasn't about volatile memecoins or speculative NFT flips. It was about fixing the pipes. We have been told that blockchain would eventually replace the slow, fee-heavy settlement systems that make moving money across borders a nightmare for founders. This week, that promise moved several steps closer to reality as the two biggest names in traditional finance, Visa and Mastercard, quietly opened the floodgates for USDC payouts.
Through a series of rollouts including Visa's Inyo initiative and Mastercard's partnership with the BVNK platform, these giants are enabling businesses in over 200 countries to receive funding and settle balances using stablecoins. This isn't just a pilot program for a few hand-picked firms in Silicon Valley. It is a fundamental shift in how the largest payment networks on the planet view digital dollars.
If you have ever tried to run a global business, you know the pain. You wait three to five days for international wires. You lose 3% to 7% on currency conversion and intermediary bank fees. You deal with the uncertainty of whether a payment was flagged by a random compliance algorithm in a time zone six hours ahead of you. By integrating USDC, Visa and Mastercard are admitting that the legacy rail system is outdated. They are building a bridge to the new rail before someone else does it for them.
What This Means for the Global Founder
For builders, this is about liquidity and velocity. When we talk about "stablecoin adoption," we usually focus on retail users buying coffee. But the real game-changer is B2B settlement. If a software company in Brazil can pay its developers in Poland via USDC through a Mastercard-linked platform, and that developer can immediately access those funds through their existing financial stack, the friction of global commerce drops to nearly zero.
Mastercard's move with BVNK is particularly telling. They aren't trying to build their own closed-loop blockchain; they are tapping into the existing ecosystem of Circle’s USDC. It’s a pragmatic approach. They realize that the infrastructure for stablecoins is already robust enough to handle enterprise-grade volume. For founders, this means you can start thinking about your treasury and your payroll in terms of stablecoins without fearing that you'll be locked out of the traditional banking system.
However, we shouldn't get ahead of ourselves. These rollouts are still subject to strict eligibility requirements and regional limits. Don't expect to flick a switch and have your entire balance sheet on-chain tomorrow. The regulatory landscape is still a patchwork of confusion, and Visa and Mastercard are, at their core, conservative entities. They are moving fast for their standards, but they are still moving with a lawyer in every room.
The End of the Middleman? Not Quite
There is a segment of the crypto community that thinks this will kill banks. I disagree. This isn't about killing the intermediaries; it’s about the intermediaries evolving to survive. Visa and Mastercard aren't going away. They are positioning themselves as the ultimate curators of these new digital rails. They want to be the ones who provide the compliance, the dispute resolution, and the user interface for stablecoin transactions.
As a builder, you need to recognize that the "middleman" is just changing shape. Instead of paying a wire fee, you might be paying a platform fee to use these new integrated USDC routes. The benefit isn't necessarily that it will be free—nothing is ever free in finance—but that it will be predictable. Predictability is the one thing founders value more than almost anything else when it comes to cash flow.
Why USDC and Not the Rest?
It is no coincidence that USDC is the asset of choice here. While USDT (Tether) still dominates in terms of pure volume and offshore trading, USDC has played the compliance game from day one. It has stayed close to regulators, maintained transparent reserves, and positioned itself as the "adult in the room." For a company like Visa, which lives and dies by its reputation with central banks and global regulators, USDC is the only logical choice.
This should serve as a signal to anyone building in the space: if you want to integrate with the legacy world, compliance isn't a hurdle; it’s the product. Circle has successfully turned a digital token into a recognized financial instrument that the world's most powerful networks trust. That is the blueprint for success in the next phase of the industry.
The Skeptic's Corner: The Practical Reality
Let’s look at the hurdles. First, the tax implications of these payouts are still a nightmare in many jurisdictions. Even if the value of USDC is pegged to the dollar, tax authorities in many countries still treat these transactions as property transfers rather than currency. Second, there is the issue of "on-ramps" and "off-ramps." Getting USDC is easy; getting it into a local currency to pay rent or taxes in a country that doesn't support digital assets is still a bottleneck.
Visa's Inyo rollout is a step toward solving this, but it’s still early days. We are in the "early adopter" phase of enterprise stablecoin use. You will likely see these payouts used first by crypto-native companies, then by high-tech startups, and eventually by mainstream e-commerce. It will take years for the local florist to care about this, but for the people building the future of the internet, it matters today.
Final Takeaway for Builders
The signal is clear: the infrastructure for a global, borderless economy is being laid by the very companies that built the current one. If you are building a platform that involves moving money, you can no longer ignore stablecoin settlement as a core feature. It is moving from a "nice to have" to a competitive necessity.
Stop looking at crypto as a separate asset class and start looking at it as a faster, cheaper set of rails for the business you are already running. Visa and Mastercard have already placed their bets. You should probably make sure your stack is ready to handle what's coming.
Read the original at CryptoSlate →