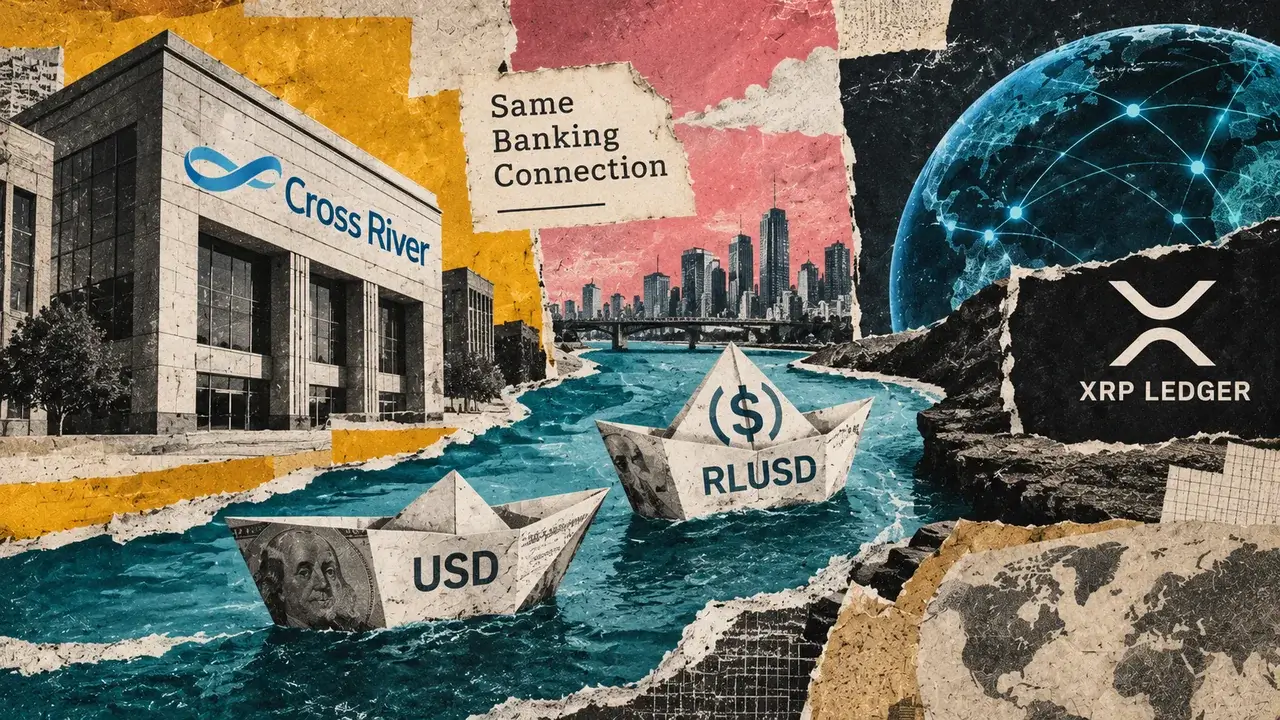
Cross River Bank just made a move that should get every fintech founder’s attention. They’ve integrated Ripple’s RLUSD stablecoin directly into their core banking stack. This isn't just another press release about a pilot program. It is a functional bridge between a regulated bank and a multibillion-dollar liquidity pool.
The Core Banking Shift
For the uninitiated, Cross River is the quiet giant behind most of the fintech apps on your phone. They handle the messy plumbing of regulated finance so startups can focus on UX. By linking $2.4 billion in RLUSD liquidity to their central ledger, they are effectively telling builders that the distinction between a 'bank wire' and a 'stablecoin transfer' is disappearing at the API level.
This matters because, for years, builders had to maintain separate silos. You had your traditional banking partner for ACH and wires, and then you had to find a crypto-native custodian or exchange for your on-chain needs. Cross River is attempting to collapse that distance. They are offering a single entry point where a fintech can move between USD and RLUSD without jumping through five different compliance hoops.
Why Ripple’s RLUSD?
Ripple has been playing the long game with regulators, even when it cost them dearly in court. The RLUSD stablecoin is their attempt to create a 'gold standard' for enterprise-grade liquidity. It is fully backed by US Treasury bills, reverse repo agreements, and cash. It isn't an algorithmic experiment; it’s a boring, stable financial instrument.
From a founder’s perspective, 'boring' is exactly what you want when building a payment stack. You don't want to wake up and find your reserve assets have de-pegged because of a code flaw. Cross River’s decision to back this specific asset suggests they are prioritizing regulatory durability over the speculative hype often found in the broader DeFi space.
The API Advantage for Builders
The real story here isn't the dollar amount—it’s the integration. By exposing this through a single API, Cross River is removing the technical friction that stops most companies from touching crypto. If you are building a cross-border remittance app, you no longer have to worry about the multi-day lag of the SWIFT network. You can settle in RLUSD nearly instantly and have it reflected in a regulated bank account.
However, we need to keep a skeptical eye on the limitations. Currently, this service is only available in specific US states. This is the classic 'regulated crypto' trap. You get the security of a bank, but you lose the permissionless nature of the blockchain. You are still playing in a walled garden; it’s just a garden with a much faster irrigation system.
The Founder's Dilemma: Speed vs. Control
If you’re a builder, you have to ask yourself: do you want to be a crypto company or a company that uses crypto? Cross River is betting that most successful founders want the latter. They want the speed of the XRP Ledger without the headache of managing private keys and regulatory filings for every state they operate in.
- Efficiency: Moving money 24/7 without waiting for banking holidays.
- Compliance: Offloading the KYC and AML burden to a bank that already has the infrastructure.
- Liquidity: Tapping into a $2.4 billion pool that is growing.
But there is a catch. When you use a centralized bank to access a stablecoin, you are still subject to their terms of service. They can freeze your API access just as easily as they can freeze a checking account. This is 'Crypto-Lite.' It is a necessary stepping stone for mass adoption, but it isn't the decentralized utopia that early Bitcoiners envisioned.
What Happens Next?
Expect to see a wave of 'Web 2.5' apps emerging from this. These will be apps that look and feel like Venmo or Revolut but use RLUSD under the hood to move value across borders. Users won't know they are using a stablecoin, and honestly, they shouldn't have to. The best technology is invisible.
The successful integration of stablecoins into core banking is the final nail in the coffin for the argument that crypto has no utility. The utility is the plumbing.
We are moving into an era where the underlying protocol matters less than the regulatory wrapper. If Cross River can prove this model works without catching the ire of the SEC or the Fed, every other regional bank will be forced to follow suit or risk losing their fintech clients to a faster, cheaper alternative.
The Skeptic’s Corner
Before we get too excited, let's look at the risks. Centralization is the obvious one. If Cross River has a bad quarter or faces a regulatory crackdown, every fintech tied to this API faces systemic risk. We saw this with the collapse of Silvergate and Signature. Dependency on a single 'crypto-friendly' bank is a single point of failure.
Founders should use this tool, but they shouldn't rely on it exclusively. Diversification of your banking stack is just as important as the code you write. Use the Cross River API for the speed, but keep a secondary rail open. The history of crypto-banking is littered with companies that thought they found a permanent partner, only to be de-banked overnight.
Takeaway for the Ecosystem
The bridge between USD and RLUSD at Cross River is a massive win for the 'Builder First' mentality. It simplifies the stack. It reduces the need for complex treasury management. It makes the 'magic' of instant global settlement accessible to anyone who can write a POST request to an API.
Keep an eye on the state-by-state rollout. The real test will be when this hits the major financial hubs that currently have stricter 'BitLicense' style requirements. If Cross River can navigate those waters, the $2.4 billion currently in RLUSD will look like pocket change compared to what's coming.
Read the original at CryptoSlate →