The High Cost of Permission
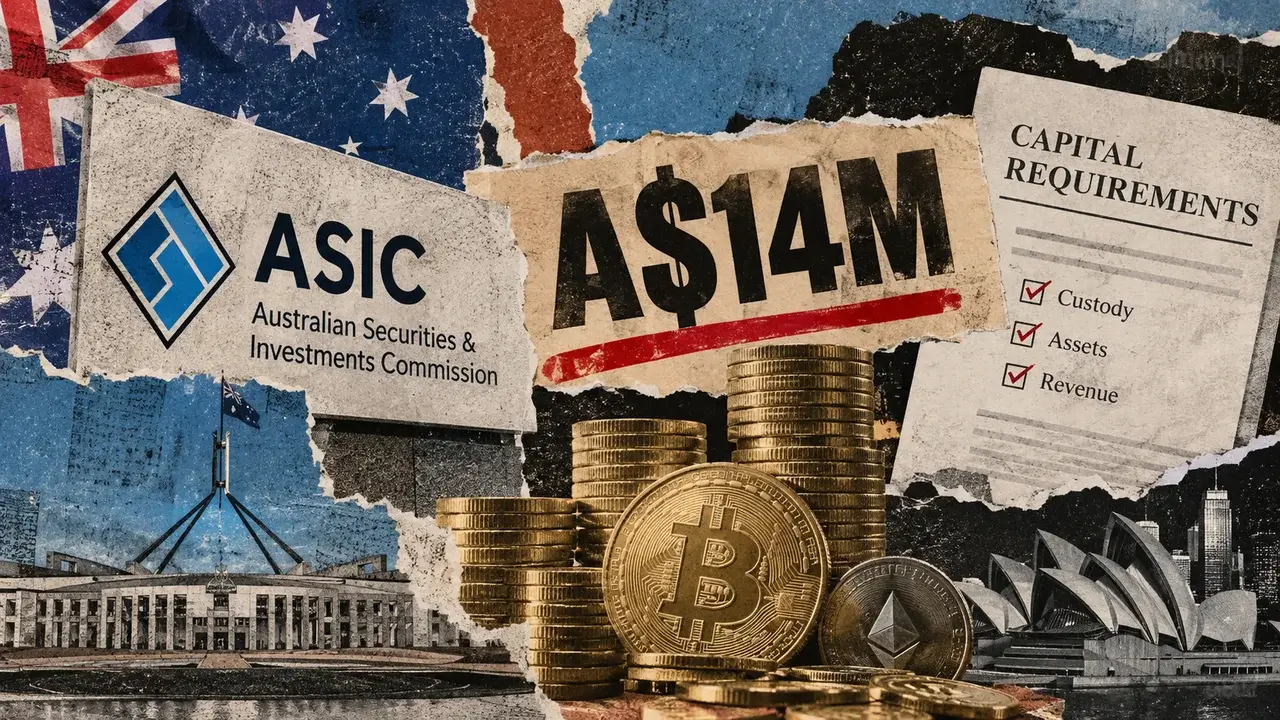
Australia used to be a place where you could build. But lately, the regulatory climate is starting to look a lot more like a gated community. The latest proposal from the Treasury isn’t just a minor adjustment to the rules; it is a structural barrier that changes who gets to play the game. They are looking at a A$14 million capital requirement for crypto platforms, a move that feels less like consumer protection and more like a mandatory exit ramp for startups.
If you are a founder in Sydney or Melbourne, the math just changed. We aren't just talking about keeping some cash in the bank for a rainy day. This is a deliberate attempt to institutionalize the industry before it has even had a chance to fully mature. The message is clear: if you don’t have deep pockets or a venture capital firm footing the bill, the Australian government doesn't think you are fit to hold a private key.
Breaking Down the Custody Floor
The core of this proposal centers on a A$200,000 custody floor, but that is really just the entry fee. The A$14 million figure is the ceiling for platforms with significant assets under management or high revenue. This creates a sliding scale of pain. The Treasury is basically saying that if you scale, you must pay. This creates a massive incentive for builders to stay small or move their operations to jurisdictions that understand the difference between risk management and wealth taxes.
What is particularly frustrating is the focus on the "outside custodian." The rules aren't just about how much money you have; they are about who you are allowed to work with. By imposing strict requirements on third-party custodians, the government is effectively narrowing the market to a handful of approved providers. For a sector that was founded on the idea of removing intermediaries, we are seeing a massive push to re-insert them into every single transaction.
What This Means for the Builder
For the person actually writing code, this is a distraction you don't need. When you are trying to solve problems like latency, UX, or protocol security, the last thing you want to worry about is whether your balance sheet meets an arbitrary government threshold. It forces founders to spend their time fundraising for the sake of compliance rather than building for the sake of the user.
We have seen this play out before in traditional finance. High capital requirements lead to consolidation. When the cost of entry is too high, the big players just buy up the small ones, or the small ones simply go bust. The result is less innovation and higher fees for the end consumer. It is the opposite of what crypto was supposed to achieve. Instead of a thousand flowers blooming, we get three or four massive, regulated hedges.
Regulation should be about behavior, not balance sheets. If a founder is acting in good faith and managing risk, the size of their bank account shouldn't be the deciding factor in whether they can operate.
The Skeptic’s View on Consumer Protection
The government will tell you this is about protecting the public from another FTX-style collapse. But let’s be honest: SBF had billions. Capital requirements don't stop fraud; they just make fraud more expensive to start. A platform can have A$100 million in the bank and still mismanage user funds or get hacked because of poor security protocols. Tying safety to a dollar amount is a lazy way to regulate.
True protection comes from transparency, on-chain proof of reserves, and smart contract audits. But regulators struggle with those concepts because they can't be measured with a simple tax form. They prefer the old-world tools of capital buffers because that is what they know. It’s like trying to regulate a spaceship using the rules of a horse and carriage.
Strategic Moves for Founders
If you are building in Australia, you have to decide if the local market is worth the overhead. For some, the answer will be yes. There is a lot of wealth in Australia and a high level of crypto adoption. But for the early-stage founder, this proposal is a flashing red light. You might need to look at offshore structures or focus on decentralized protocols that don't fall under the definition of a "custodial platform."
There is also the question of the revenue test. The proposal isn't just looking at how much crypto you hold; it's looking at how much money you make. This is a double whammy. If you are successful, the government moves the goalposts. It creates a "success tax" that punishes growth. Builders need to be looking at their five-year projections now to see if they can even afford to be successful under these rules.
A Glimpse of the Future
Australia isn't alone in this, but they are being particularly aggressive. We are seeing a global trend where the "middle class" of crypto companies is being squeezed out. You will eventually have the massive, compliant giants like Coinbase or Binance, and then you will have the pure DeFi protocols. The space in between—the innovative startups that bridge the two—is being regulated out of existence.
As an industry, we need to push back against the idea that size equals safety. We should be advocating for regulations that reward technical excellence and transparency rather than just rewarding the companies with the biggest treasury. If we don't, we are going to end up with a crypto industry that looks exactly like the banking system we were trying to replace.
The Bottom Line
The A$14 million rule is a gatekeeping mechanism. It is designed to ensure that only the established players can survive in the Australian market. For founders, the takeaway is simple: either raise a massive amount of capital early, or build something that doesn't require a custodial license. The days of building a crypto exchange in your garage are officially over in Australia.
Read the original at CryptoSlate →