The Mathematics of Conviction
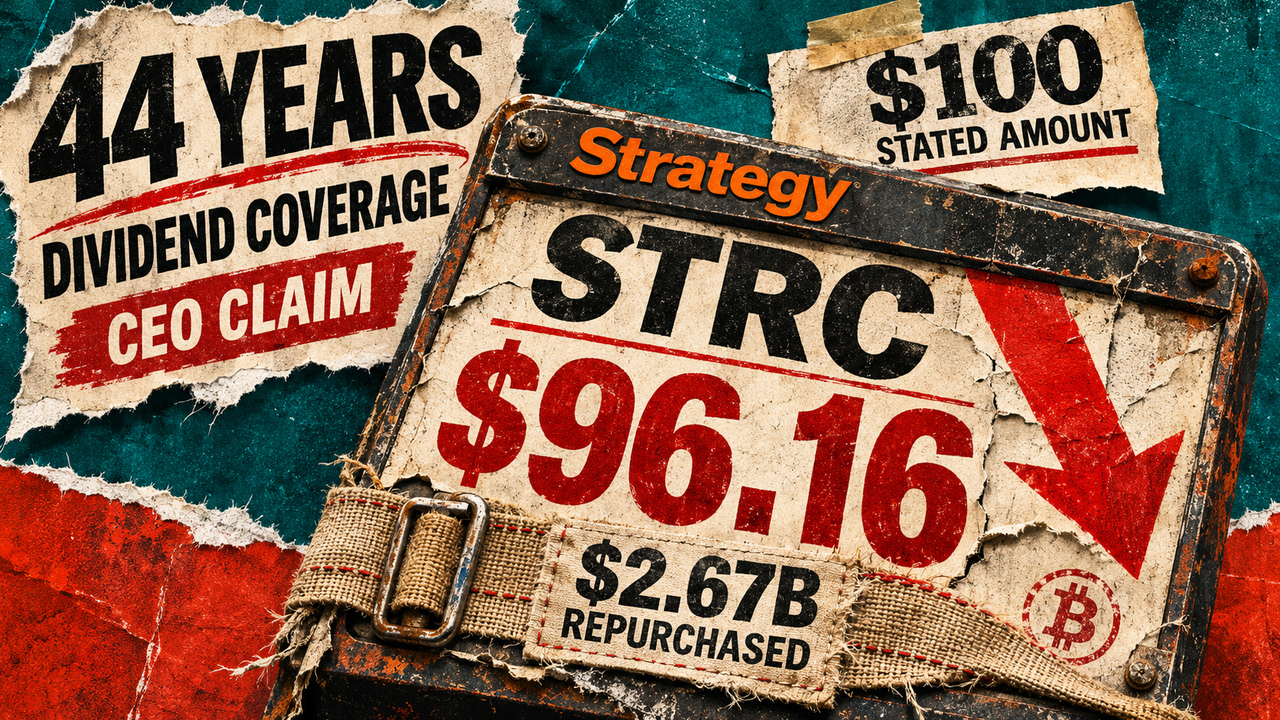
Michael Saylor has essentially bet the farm, the neighbors' farm, and the future of his descendants on a single digital asset. We all know the story of Strategy—formerly MicroStrategy—and its relentless pivot from a middling enterprise software firm to a massive Bitcoin holding company. But recently, a crack appeared in the armor that usually deflects every arrow the bears fire. The STRC preferred stock, the very instrument designed to signal stability and long-term yield, dipped below its $100 par value, hitting lows we haven't seen since the summer.
For those of us building in this space, this isn't just another price chart. It is a lesson in market sentiment versus corporate signaling. Strategy has been shouting from the rooftops about their multi-billion dollar repurchase campaign, effectively trying to put a floor under their own valuation. When the market ignores a buyback and sells anyway, it tells you that the investors are pricing in a risk that the leadership isn't acknowledging publicly.
The Yield Trap
The promise of forty-four years of dividends is a bold claim. In the tech world, forty-four years is an eternity. We barely know what the AI landscape will look like in forty-four months. By promising such a long-dated return, Saylor is attempting to frame Strategy not as a volatile tech play, but as a foundational institution—a digital version of a legacy utility company or a sovereign wealth fund. The problem is that the market currently sees the STRC stock as a leveraged bet on Bitcoin volatility, not a boring dividend play.
When the price fell to $95.51, it pushed the annualized yield higher, which usually attracts buyers looking for a bargain. The recovery to $96.16 shows there is some support, but the fact that it remains below the $100 stated amount is a psychological blow. It suggests that despite the massive cash injections and the buyback promises, the market isn't entirely convinced that the company can sustain this level of aggressive treasury management if the underlying asset—Bitcoin—doesn't behave perfectly.
What Builders Need to Understand
As a founder, you might look at Strategy and see a masterclass in treasury management. You see a CEO who found a way to turn a legacy business into a global powerhouse by leveraging debt and equity to buy the hardest money on earth. But there is a flip side to this. When you tie your corporate identity so closely to the price of a single, volatile asset, your traditional financial instruments begin to behave like that asset.
Preferred stock is supposed to be the safe, boring part of the capital stack. It’s for the investors who want priority on dividends and a clear path to liquidation. When your "safe" stock starts swinging and dipping below par, it creates a ripple effect. It makes it harder to raise future rounds of debt or equity on favorable terms because you’ve proven that even your stability-focused instruments are susceptible to the gravity of the crypto markets.
The market doesn't care about your forty-year plan if the next forty days look uncertain.
The Credibility Gap
Saylor’s conviction is his greatest strength, but for the average builder, it’s a dangerous path to follow blindly. The decline in STRC stock despite a massive buyback is a reminder that you cannot simply buy your way into market confidence. A buyback is a tool, not a cure. If the broader market believes your valuation is disconnected from the reality of your balance sheet or your future earnings potential, they will sell through your buyback wall every single time.
We have to look at the mechanics of why this happened. The yield on these shares became more attractive as the price dropped, but the drop itself signals a lack of trust in the underlying collateral. If the Bitcoin treasury were viewed as an absolute, unbreakable safety net, the preferred shares would never trade below par. The fact that they did suggests that institutional investors are still hedging their bets on whether Strategy can navigate a prolonged sideways market or a significant correction.
The Takeaway for the Ecosystem
We are entering a phase where "holding Bitcoin" is no longer a unique enough value proposition for a public company. The novelty has worn off. Now, the market is looking for sustainability. For builders, the lesson is clear: Diversification of thought and treasury is still a virtue. While extreme conviction makes for great headlines and a loyal Twitter following, it creates systemic risks that can haunt your cap table for decades.
If you are building a startup and thinking about your treasury, remember that your equity and your debt are promises you make to your stakeholders. If those promises are perceived to be at the mercy of a volatile market, your cost of capital will go up, and your flexibility will go down. Strategy is currently finding out that even a multi-billion dollar war chest isn't always enough to stop the market from asking 'what if?'
Watch the $100 mark closely. If Strategy can’t keep their preferred shares at par during a period of relative strength for Bitcoin, it raises serious questions about what happens when the next real winter arrives. Credibility is built in the green but tested in the red, and right now, the tests are getting harder.
Read the original at CryptoSlate →