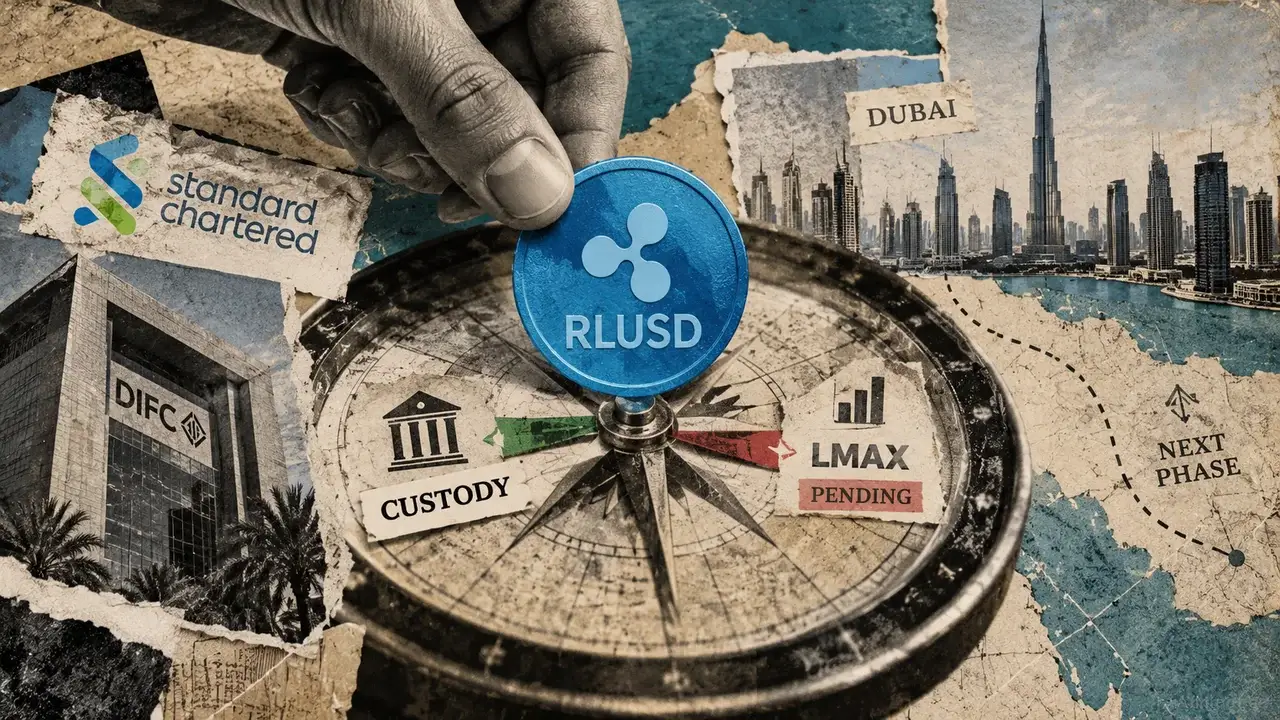
We have reached a weird moment in the evolution of digital finance. For years, XRP was the outsider, the asset that banks were allegedly going to use but never quite did. Now, Standard Chartered is opening its vaults for RLUSD, Ripple's dollar-pegged stablecoin. This is happening through their Dubai International Financial Centre branch, and it is a move that founders should be watching closely.
The Institutional Stamp of Approval
The headline here is simple: a major global bank is now custodying a stablecoin issued on the XRP Ledger. This isn't a pilot program or a vague press release about exploring the blockchain. It is a live service for eligible clients. Standard Chartered is putting its balance sheet and reputation behind the security of RLUSD.
For those of us building in this space, this represents a significant shift in risk assessment. When a bank like Standard Chartered enters the fray, they aren't just looking at the code. They are looking at the regulatory compliance, the reserves, and the durability of the underlying network. Their decision to support RLUSD suggests that the institutional world is finally getting comfortable with the XRP ecosystem as a legitimate rail for value, not just a speculative token.
Why the DIFC Matters
The choice of the Dubai International Financial Centre (DIFC) as the hub for this service is not accidental. Dubai has positioned itself as the grown-up in the room when it comes to crypto regulation. By operating under the Dubai Financial Services Authority, Standard Chartered provides a level of comfort that you simply cannot get in more litigious or uncertain jurisdictions.
For builders, this is a lesson in geography. If you are developing products that require high-level banking integration, the jurisdiction you choose dictates your ceiling. Ripple spent years fighting regulatory battles in the US, but the actual utility is being unlocked in places where the rules of the road are clearly defined.
The Numbers Behind the Move
Standard Chartered didn't just wake up and decide to support RLUSD for fun. There is a massive surge in capital moving through these channels. We are looking at a quarterly increase of over $765 million in related activity. That kind of growth is hard for a legacy bank to ignore. They follow the fees, and right now, the fees are in stablecoin custody and settlement.
However, we need to stay grounded. While the custody piece is live, the much-touted LMAX collateral link—which would theoretically connect this liquidity to broader institutional trading—remains conditional and lacks a firm date. In this industry, "conditional" often means "we are waiting for something to break or someone to sue us." It is a reminder that while the pipes are being laid, the water isn't flowing at full capacity yet.
The Founder's Perspective
If you are a founder, you shouldn't look at this as a reason to go all-in on XRP. Instead, look at it as a blueprint for institutional adoption. Ripple didn't win over Standard Chartered by being the fastest or the cheapest. They won by building a stablecoin that mirrors the compliance standards of the banking world. RLUSD is designed to be boring. It is over-collateralized, transparently audited, and fits into the existing ledger systems of traditional finance.
The skepticism comes in when we look at the actual utility for the average user. This is a top-down integration. It benefits hedge funds, family offices, and large-scale payment processors. It doesn't necessarily make it easier for a small startup to bypass the traditional banking system. In fact, it reinforces the system by bringing the digital assets inside the bank's walls.
The Risks of Centralized Custody
There is a paradox here that we have to acknowledge. The whole point of crypto was to remove the need for institutions like Standard Chartered. By putting RLUSD in a bank vault, we are essentially turning a blockchain asset back into a traditional bank deposit. If the bank freezes the account, the fact that it sits on the XRP Ledger doesn't matter to the end user.
We are seeing the creation of a tiered crypto economy. On one side, you have the permissionless, decentralized world. On the other, you have the "banked" crypto world. This move by Standard Chartered is a massive win for the latter, but it does very little for the former. As a builder, you have to decide which side of that fence you are building on.
What This Means for the XRP Ledger
For a long time, the XRPL was seen as a ghost town for developers compared to Ethereum or Solana. The introduction of a bank-backed stablecoin changes that narrative. Liquidity is the lifeblood of any network. If Standard Chartered is funneling hundreds of millions of dollars into RLUSD on the XRPL, it creates an environment where DeFi protocols and payment apps on that chain suddenly have a stable, trusted base layer to build upon.
It also puts pressure on other stablecoin issuers. Tether and Circle have dominated the market, but neither has the same level of deep-rooted integration with legacy banking giants that Ripple is currently cultivating. This isn't just a competition of technology; it's a competition of trust and legal frameworks.
Final Takeaway for Builders
The takeaway here is that the "institutional wave" isn't a single event; it's a slow grind of custody agreements and regulatory approvals. Standard Chartered's move is a signal that the infrastructure is ready for serious money. If you are building tools for the next generation of finance, you need to ensure your stack can talk to these institutional vaults.
Don't get distracted by the hype of the $765 million surge. Focus on the fact that a legacy bank found a way to make a stablecoin fit their risk model. That is the real innovation. The future of this space isn't just about decentralization; it's about the points where the old world and the new world shake hands. Standard Chartered just extended their hand.
Read the original at CryptoSlate →