Fintech founders often talk about regulatory hurdles as if they are finish lines. You run the race, you jump the fences, and once you get the license, you win. But the reality on the ground in Europe right now suggests that getting the license is just the invitation to a much larger, much more complicated fight.
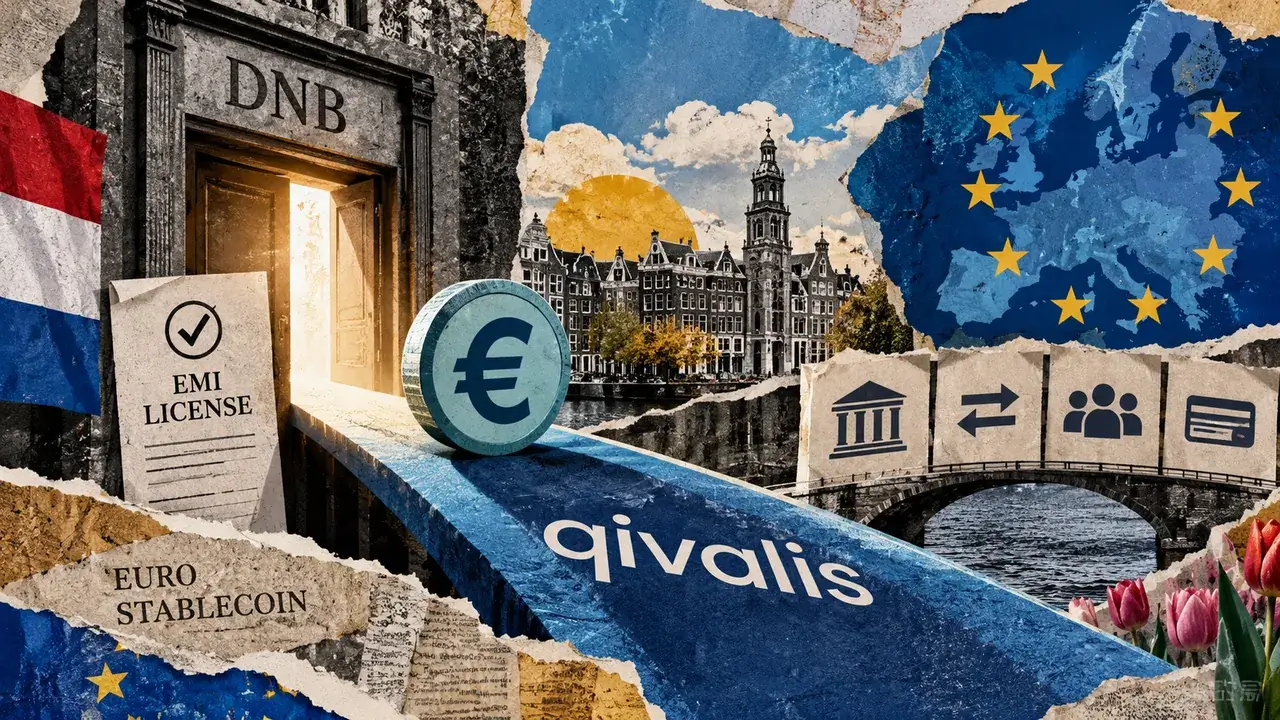
Take Qivalis as the latest example. This French startup recently announced they secured an Electronic Money Institution (EMI) license from the Dutch Central Bank. In the old world, this would be the green light to start moving money. In the new world of the Markets in Crypto-Assets (MiCA) regulation, it is basically a permit to keep waiting.
The Permission Paradox
Getting a nod from the Dutch Central Bank is no small feat. The Netherlands is notorious for being one of the stricter jurisdictions in the Eurozone. For Qivalis, this license was supposed to be the foundation for their EURQ stablecoin. They want to issue a digital euro that actually complies with the law, which is a noble goal in an industry that has spent a decade trying to outrun the law.
However, the company immediately had to temper the celebration. Even with the EMI license in hand, they cannot launch. Why? Because MiCA has created a tiered system of requirements that turns a standard fintech launch into a multi-phase bureaucratic marathon. They are currently stuck in the white-paper phase, waiting for regulatory approval on their specific asset-referencing documentation before a single token can hit a wallet.
Why MiCA is a Double-Edged Sword for Builders
For those of us building in the space, MiCA was sold as "clarity." We were told that once the rules were written, we would finally know how to play the game. And to be fair, clarity is better than the regulatory-by-enforcement chaos we see in the United States. But clarity comes with a heavy price tag: overhead.
Qivalis is facing the reality that an EMI license is only half the battle for stablecoin issuers. Under the new EU framework, if you want to issue a token pegged to a fiat currency, you aren't just a tech company anymore; you are a quasi-bank with the reporting requirements to match. You need massive capital reserves, highly specific custody arrangements, and a level of transparency that most startups simply aren't built for.
The Innovation Tax
What does this mean for the average founder? It means the cost of entry just went up by a factor of ten. If you want to build a stablecoin or a payment bridge in Europe, you can no longer bootstrap your way through a minimum viable product. You need a legal team before you need a dev team.
Qivalis is essentially a test case for whether a smaller player can survive this environment. The big players like Circle are already positioned. The giants have the balance sheets to absorb these compliance costs. For the smaller founders, the "MiCA moat" is becoming very real. It’s not that the rules are impossible to follow; it’s that they are expensive to implement.
The Dutch Factor
It is also worth noting that Qivalis chose the Netherlands over their home turf in France. This is a strategic move we are seeing more often. Founders are shopping for regulators who are tough but predictable. The Dutch have a reputation for being no-nonsense, but if you pass their sniff test, you generally have a stronger standing when you try to passport that license across the rest of the EU.
But even with that strategic advantage, the MiCA rollout is slowing everything down. The transition period between old national rules and the new EU-wide mandate is creating a vacuum where companies have the permission to exist, but not the permission to operate. It’s a frustrating middle ground where you’re burning runway while waiting for a regulator to read your white paper.
The Founder Perspective
I’ve talked to a lot of builders who are looking at Europe as the new promised land because of the regulatory framework. My advice is always the same: don't mistake regulation for support. MiCA is designed to protect the financial system, not to make your startup successful. It is a gatekeeper mechanism.
If you are planning to issue an asset in this environment, you need to be prepared for the "Qivalis Delay." You might do everything right, you might win the license you spent two years chasing, and you might still be told to sit on your hands for another six months while the paperwork settles.
The biggest risk to a crypto startup in 2024 isn't the technology failing or the market crashing; it is the regulatory clock running longer than your bank account.
What to Watch Next
The next few months will be telling for Qivalis and the broader European stablecoin market. They are aiming for a launch "in the coming months," which is fintech-speak for "as soon as the government lets us." Watch their white-paper publication closely. The level of detail required by the Dutch authorities will set the bar for every other stablecoin founder trying to enter the Eurozone.
We are entering an era of "Institutional Crypto," where the winners aren't the ones with the fastest code, but the ones with the most patience. Qivalis has the license, which is a win, but the real test is whether they can survive the bureaucratic weight of the very system they worked so hard to join.
The Takeaway
Regulation provides a path, but it doesn't provide a shortcut. If you're building in the EU, budget twice as much time and three times as much money for compliance as you think you need. The license is just the beginning of the paperwork, not the end of it.
Read the original at CryptoSlate →