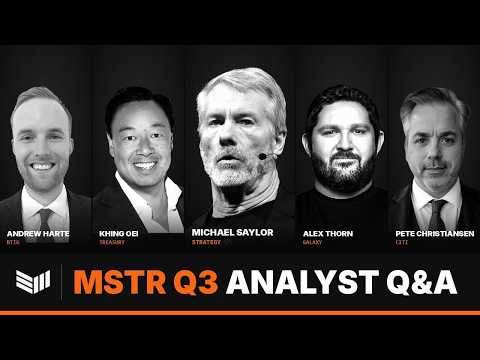
We have reached a weird inflection point in the markets where MicroStrategy is no longer a software company that happens to own Bitcoin. It is a full-blown financial laboratory. During the recent Q3 earnings call, Michael Saylor and Phong Le spent less time talking about enterprise analytics and more time explaining how they are essentially building a central bank for the digital age. For builders and founders, this is the blueprint for how aggressive capital allocation can rewrite the rules of a public company.
The Debt Arbitrage Machine
The core of the conversation revolved around digital credit and the financialization of Bitcoin. Saylor isn't just sitting on a pile of sats; he is using those sats as the ultimate collateral to access incredibly cheap capital. When analysts ask about preferred shares or issuing debt at par, they are really asking how long this game can last. The answer, according to the MicroStrategy playbook, is as long as the volatility of Bitcoin remains higher than the cost of the debt they use to buy it.
For those of us building in the space, this is a lesson in leverage. Most startups are terrified of debt. We were taught that VC equity is the only way to scale. But Saylor is showing that if you have a high-conviction asset that the rest of the world is slow to understand, you can use traditional financial instruments to corner the market. It is a bold, albeit risky, strategy that turns a boring software firm into a high-octane Bitcoin proxy.
Understanding the Stretch Strategy
One of the more technical points brought up during the Q&A was the concept of 'Stretch' or STRC at par. This gets into the weeds of how they structure their preferred offerings. Essentially, they are looking for ways to capture the upside of Bitcoin without giving away the keys to the kingdom. By issuing instruments that can be converted or settled in a way that protects the company’s core Bitcoin stack, they are creating a defensive moat made of math.
If you are a founder looking at your balance sheet, you might not be able to issue billions in convertible notes, but you can learn from the philosophy. Saylor is prioritizing the long-term accumulation of a scarce resource over short-term quarterly earnings stability. He is willing to look 'wrong' to Wall Street for years if it means he is 'right' on the ledger in the end. This is a builder mindset, even if it is happening in the C-suite of a public entity.
Bitcoin as a Financial Rail
The most important takeaway for the AI and crypto integration crowd is the discussion on financialization. Saylor and Le are anticipating a world where Bitcoin is the base layer for all digital credit. They are positioning MicroStrategy not just as a holder, but as an intermediary that understands how to move value across this new rail better than the big banks do.
The goal isn't just to own Bitcoin; it is to become the infrastructure through which Bitcoin interacts with the legacy financial system.
This is where the skepticism should kick in for the average builder. While the strategy looks brilliant during a bull run, it relies on the permanent appreciation of a single asset. If you are building a product that depends on this kind of macro-acrobatics, you need to be aware of the 'black swan' risks. Saylor has the treasury to weather a storm, but most startups do not. The financialization of Bitcoin is inevitable, but the road there is paved with liquidated entities that moved too fast with too much leverage.
What Builders Should Watch
There are three things I’m keeping an eye on following this earnings call. First, the appetite for digital credit. If MicroStrategy can continue to find buyers for their debt, it means the institutional world is growing more comfortable with Bitcoin as collateral. That’s good for everyone building DeFi or payment layers.
Second, the regulatory response to this kind of 'infinite loop' buying. At some point, regulators might take a closer look at how a public company is essentially acting as an unregulated Bitcoin ETF with a software company attached. Builders in the compliance space should see this as a massive opportunity to provide transparency tools.
Third, the transition from 'holding' to 'operating.' Saylor hinted at the fact that they are looking at Bitcoin not just as a reserve, but as a productive asset. This means we might see MicroStrategy start to fund or integrate with layer-2 solutions that increase the utility of their holdings. If you are building on Lightning or other scaling protocols, Michael Saylor might eventually become your most important customer.
The Honest Truth
Let’s be real: MicroStrategy is a giant experiment. It is the first time we have seen a company try to 'out-Bitcoin' Bitcoin itself. For a founder, the takeaway isn't to go out and buy a bunch of BTC on your corporate credit card. The takeaway is to look for the asymmetries in your market. Saylor found an asymmetry between the value of Bitcoin and the cost of fiat debt. He is exploiting it until it no longer exists.
Your job as a builder is to find your own asymmetry. Maybe it is the gap between AI capability and current enterprise workflows, or the gap between crypto security and user experience. Whatever it is, you need to be as relentless about attacking that gap as Saylor is about his Bitcoin stack. Just remember that when you play with leverage, the margin for error disappears. MicroStrategy is a masterclass in conviction, but it is also a reminder that in this industry, you are either the hammer or the nail.
Read the original at Bitcoin Magazine →