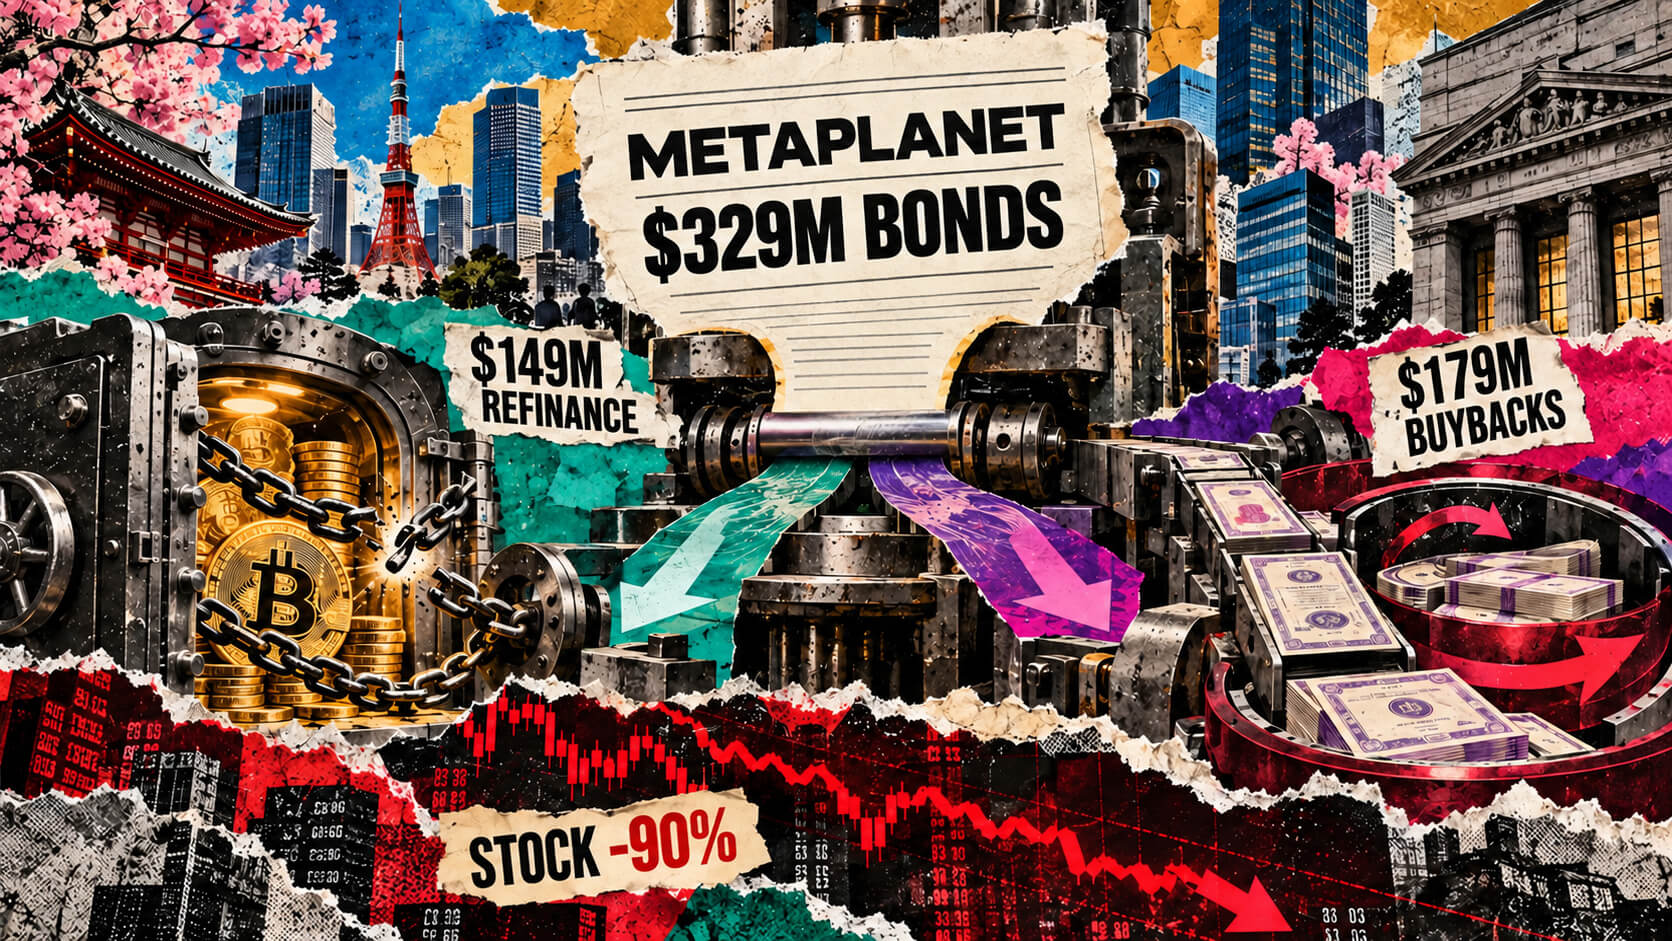
Metaplanet has become the go-to case study for the MicroStrategy playbook in Asia. If you have been following the Japanese markets, you know they have been aggressively stacking Bitcoin to combat the long-term devaluation of the yen. But the market just gave them a brutal reality check. After their stock price cratered nearly 90% from its recent highs, the leadership team is doing exactly what you would expect from a conviction-driven treasury: they are doubling down.
The $329 Million Pivot
The company recently announced a plan to raise approximately 52 billion yen, which is roughly $329 million, through the issuance of unsecured, zero-coupon Euro-yen convertible bonds. These bonds are set to mature in 2031. For builders and founders, the structure of this deal is more interesting than the dollar amount. Zero-coupon means they are not on the hook for regular interest payments, which preserves cash flow for their primary mission—stacking sats.
The capital has a very specific roadmap. They are looking to refinance Bitcoin-backed loans and, perhaps more importantly for their optics, fund a massive share buyback. When your stock drops 90%, you have two choices: panic and pivot, or signal to the market that you believe the equity is fundamentally undervalued. Metaplanet chose the latter.
Why the 90% Crash Happened
To understand why they are raising this money now, we have to look at the volatility of the 'Bitcoin Treasury' model. When a public company ties its valuation to a volatile digital asset, the stock becomes a leveraged play on that asset. When the Japanese market experienced recent tremors and Bitcoin saw a cooling-off period, the speculative premium on Metaplanet evaporated.
For a founder, this is the danger of the 'proxy' trade. If your company is viewed simply as a way to buy Bitcoin on a local stock exchange, your stock will often overshoot on the way up and over-correct on the way down. Metaplanet’s peak was fueled by hype; the crash was the market returning to a sober reality. This buyback is an attempt to put a floor under that decline.
Refinancing the Bitcoin Debt
The most tactical part of this announcement is the refinancing of Bitcoin-backed loans. Using Bitcoin as collateral is a common move for treasuries, but it carries liquidation risks if the price of BTC drops too sharply. By issuing convertible bonds to pay off these loans, Metaplanet is essentially moving from 'at-risk' debt to 'strategic' debt.
In the startup world, we talk a lot about runway. In the crypto treasury world, runway is measured by how much breathing room you have before a margin call. This $329 million infusion buys them years of breathing room. It turns a short-term liquidity concern into a long-term capital structure play.
The Founder Perspective: Conviction vs. Math
There is a fine line between visionary leadership and reckless gambling. Critics will say Metaplanet is catching a falling knife. They see a company whose core business is increasingly overshadowed by a volatile balance sheet. However, if you look at this from a builder's perspective, they are following a proven script. They are using the tools of traditional finance—convertible bonds and debt markets—to acquire a hard asset that they believe will outperform the yen over a decade.
The move to buy back shares at a 90% discount is particularly gutsy. It tells shareholders that the management believes the Bitcoin on the balance sheet is worth significantly more than the current market cap of the company. It is an arbitrage play on their own reputation.
What This Means for the Ecosystem
Metaplanet's success or failure will dictate how other Japanese and Asian firms handle their reserves. If they can weather this 90% drawdown and come out the other side with a stronger balance sheet, they will have provided a blueprint for corporate Bitcoin adoption in high-inflation or currency-weak environments. If the bonds fail to attract interest or if the buyback doesn't stabilize the price, it will serve as a warning label for the 'MicroStrategy 2.0' movement.
- Capital Efficiency: Moving from collateralized loans to unsecured bonds is a massive win for balance sheet flexibility.
- Market Sentiment: A share buyback after a 90% drop is the ultimate signal of insider confidence.
- Long-term Horizon: The 2031 maturity date shows they are playing a ten-year game, not a ten-week game.
The Takeaway
Don't get distracted by the 90% stock crash. That is just market noise and the result of over-leveraged retail traders getting flushed out. The real story is the transition of Metaplanet from a speculative stock to a sophisticated financial entity that knows how to use debt to its advantage. They are shifting the risk from their Bitcoin holdings to their bondholders. For builders, the lesson is clear: when the market hates your stock but you believe in your assets, use the tools of finance to buy yourself more time.
Read the original at CryptoSlate →