Liquidation is usually a signal to take a walk, grab a coffee, and re-evaluate your life choices. For most builders and disciplined traders, a six-figure wipeout acts as a cold bucket of water. It is a moment of forced sobriety where the market tells you that your assumptions were wrong and your leverage was dangerous. But for the heavy hitters in the decentralized finance space, the rules of psychological gravity seem to work differently.
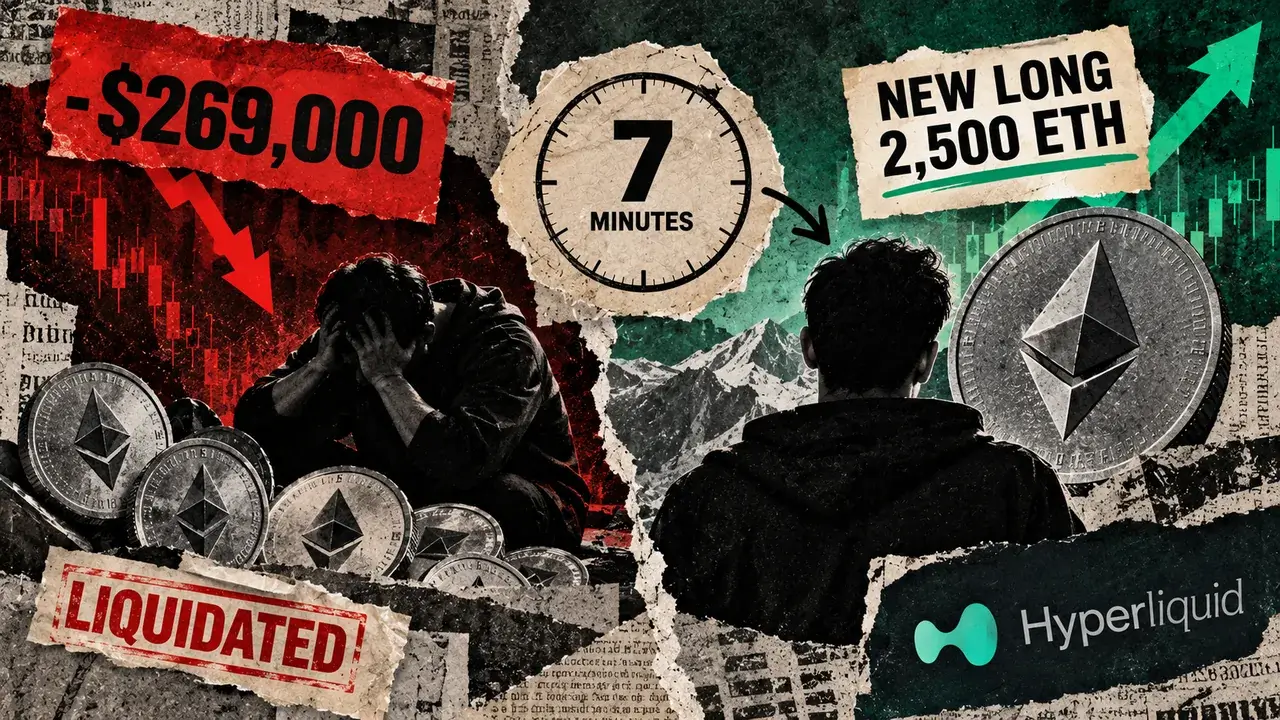
Early on October 15, the wallet widely associated with Machi Big Brother took a significant hit on Hyperliquid. The exchange's automated systems force-liquidated a position of 1,650 ETH. The loss was not just a rounding error; it totaled roughly $269,000. In a market where every basis point counts, losing a quarter-million dollars in a single automated sweep is a loud, public failure. However, what happened next is far more interesting for those of us watching how liquidity moves in this ecosystem.
The Seven-Minute Rebound
Most people expect a cooling-off period after a liquidation. You wait for a new trend to form, or at least for the volatility to settle. Instead, this specific wallet waited exactly seven minutes before jumping back into the fire. By 13:16 BST, a new long position was opened, this time for 2,500 ETH. This is not just recovery; it is a doubling down.
For a founder or a developer looking at this behavior, it is easy to dismiss it as simple gambling. We see this all the time in crypto—high-net-worth individuals treating decentralized perps like a high-stakes casino. But if you look deeper at the mechanics of platforms like Hyperliquid, this behavior reveals a specific type of market confidence (or perhaps overconfidence) that defines the current state of on-chain trading.
Why Builders Should Care About Whale Tilt
When a major player gets liquidated and immediately re-enters with a larger position, they are creating a massive target on their back. In the world of transparent on-chain data, everyone can see the entry price, the liquidation price, and the size of the collateral. This creates a specific kind of feedback loop that developers of DeFi protocols need to account for: the "revenge trade" liquidity.
If you are building a decentralized exchange or a lending protocol, you have to realize that a significant portion of your volume comes from this specific psychological profile. These are not users looking for 5% annual yields. They are users who view a $269,000 loss as a temporary setback and an opportunity to capture a local bottom. The technical challenge for platforms is ensuring that these massive, rapid-fire shifts in position do not create systemic risk for the protocol's liquidity providers.
The Illusion of Bottom-Fishing
The logic behind an immediate re-entry is usually based on the idea that the liquidation itself was the "final flush." The theory is that once the big positions are cleared out, there is no one left to sell, and the price must go up. It is a common trope in trading circles. By opening a 2,500 ETH long just minutes after being cleaned out, the trader is betting that they were right about the direction, just wrong about the timing and the leverage ratio.
However, the market rarely cares about your timing. For builders, the takeaway here is about the volatility of intent. When we design smart contracts, we often assume rational actors. We assume users will protect their capital. But the Machi incident shows that capital efficiency is often secondary to market presence. High-leverage users are often more concerned with staying in the game than they are with the cost of the entry.
The Founder's Perspective on Leverage
I have spent a lot of time talking to founders who are building the next generation of perps. The goal is always to create a "fairer" market. But cases like this remind us that the market is only as fair as the participants are disciplined. When a single entity can churn through millions in volume within minutes of a liquidation, it creates a skewed version of price discovery.
It also highlights a massive opportunity for AI-driven risk management. Imagine a protocol that detects "tilt" behavior—much like a poker site might—and adjusts requirements or provides warnings. While that goes against the permissionless ethos some hold dear, it might be the only way to protect the broader ecosystem from the radioactive fallout of a truly massive liquidation cascade.
The Real Cost of Being Early
The $269,000 loss is the headline, but the real story is the friction. Every time a position is liquidated and reopened, fees are paid, slippage is incurred, and the house (the protocol and its LPs) wins. The trader is effectively paying a massive premium to maintain their bias. For those of us building tools for these traders, the focus shouldn't just be on providing more leverage, but on providing better visibility into why these liquidations happen in the first place.
The market can stay irrational longer than you can stay solvent, but in crypto, some players have enough solvency to outlast their own irrationality.
We see this cycle repeatedly. A whale gets caught in a squeeze, the position vanishes, and a new one appears before the transaction hash is even cold. It creates a facade of liquidity that can vanish the moment the whale decides they have had enough. Builders need to be wary of building on top of this "ghost liquidity" that is driven by ego and revenge rather than fundamental market shifts.
What to Watch Next
As we watch this specific ETH long play out, we need to look at the funding rates on Hyperliquid and other on-chain venues. If the broader market starts following this lead, we could see a massive build-up of long interest that is highly sensitive to even small downward movements. For founders, the move is to watch the liquidation levels of these massive wallets. They act as magnets for price action.
If you are building in this space, do not mistake high volume for high adoption. A single trader losing and then re-betting $269,000 creates a lot of noise in the data. Your job is to filter out that noise and build systems that survive the volatility, even when the biggest players on your platform are acting with zero regard for risk management.
The Takeaway
The Machi liquidation and immediate re-entry is a masterclass in high-stakes market psychology. It shows that for some, the blockchain is less of a financial ledger and more of a scoreboard. For builders, the lesson is clear: design for the degenerate, but protect the protocol. The users who provide the most volume are often the ones with the least amount of self-preservation. If your system depends on them acting rationally, you have already lost.
Read the original at CryptoSlate →