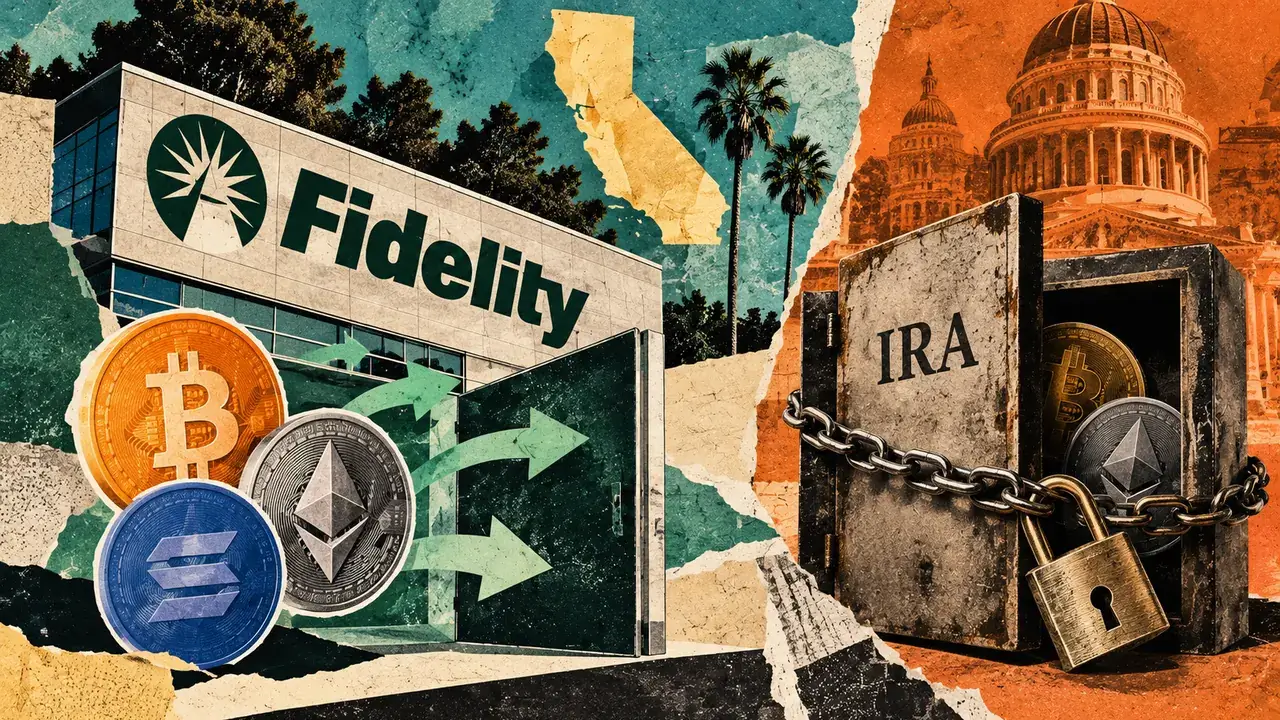
Fidelity Digital Assets just settled with California regulators for half a million dollars. On the surface, it looks like another routine compliance cost for a legacy giant dipping its toes into the crypto space. But if you look at the mechanics of the settlement, it reveals a massive gap between the promise of decentralization and the reality of institutional custody.
The core of the dispute centers on how Fidelity communicates with its retail users. Under the terms of the agreement, Fidelity has to be much more transparent if it ever decides to flip the switch and shut off its retail transfer features. If you are building in this space, this should sound a few alarms. It shows that even the most 'crypto-forward' legacy institutions are still struggling to treat digital assets as anything other than restricted internal ledger entries.
The Illusion of Ownership
For founders and developers, the phrase 'not your keys, not your coins' isn't just a meme; it is the fundamental technical requirement for a trustless system. Fidelity, however, operates on a completely different premise. When you buy Bitcoin or Ether through a legacy brokerage, you are buying exposure, not necessarily the asset itself. The California settlement forces Fidelity to admit this reality more clearly.
The settlement explicitly leaves IRAs out of the wallet-transfer terms. If you hold crypto in a Fidelity retirement account, you are effectively locked in. There is no 'transfer to cold storage' button for your 401k Bitcoin. This creates a tiered class of digital ownership where the most tax-advantaged accounts are also the most restricted.
Why Builders Should Care
We often talk about 'onboarding the next billion users.' The assumption is that institutions like Fidelity will be the gateway. But this settlement proves that these gateways are currently one-way streets. As a builder, if you are relying on institutional APIs or custodial partnerships, you need to understand that these platforms are optimized for compliance and 'safety,' not for the portability that defines the crypto ethos.
The settlement also preserves Fidelity's right to maintain 'security restrictions.' In plain English, this means they can still freeze transfers or block addresses at their own discretion. While this is marketed as protection against fraud, it is functionally no different from the traditional banking system. For those of us building decentralized finance protocols, this is a reminder that 'Institutional DeFi' is an oxymoron until we solve the custody problem.
The Settlement Details
Fidelity isn't just paying a fine; they are agreeing to a new set of disclosure rules. They have to provide clear notice if they ever decide to end the feature that allows retail users to move crypto out of their Fidelity accounts. This is a reactive measure by regulators. It suggests that the California Department of Financial Protection and Innovation is worried about 'walled gardens' becoming permanent traps for retail capital.
- Fidelity must notify users of changes to transfer capabilities.
- IRA accounts remain excluded from easy transfer protocols.
- Security overrides remain at the sole discretion of the institution.
- The $500,000 fine is a slap on the wrist, but the precedent is what matters.
From a founder's perspective, this settlement is a market signal. It shows there is a massive, underserved demand for compliant self-custody. Users want the tax benefits of an IRA and the security of a legacy brand, but they also want the utility of a hardware wallet. Right now, no one is giving them both.
A Skeptical Look at 'Consumer Protection'
Regulators claim these settlements protect consumers. I argue they mostly protect the status quo. By focusing on disclosures rather than interoperability, the settlement allows Fidelity to continue operating a closed loop. It satisfies the letter of the law while ignoring the spirit of what digital assets were designed to do.
If I were building a crypto-focused fintech app today, I would be looking closely at these exclusions. The fact that IRAs are sidelined in these transfer agreements is a huge opportunity. Someone is going to figure out how to bridge the gap between regulated retirement vehicles and true on-chain ownership without triggering a massive tax event. Fidelity clearly hasn't done it yet.
Institutions are not building for the sovereign individual; they are building for the sovereign balance sheet.
The Takeaway for the Ecosystem
We shouldn't view this settlement as a sign that crypto is 'maturing' in the way we want it to. It is maturing into a version of the old system. The friction between Fidelity and California regulators is a preview of the next decade of legal battles. We are moving from 'Is this a security?' to 'Who actually controls the private keys?'
For the builders in the room: don't wait for the big banks to build the infrastructure of the future. They are too busy settling with regulators over the infrastructure of the past. The real innovation will happen in the gaps these settlements leave behind—like making retirement assets as portable as a standard wallet address.
Fidelity's $500,000 fine is just the cost of doing business. But the restrictions they maintained in the process are the real story. They are a roadmap of exactly where the traditional financial system is refusing to innovate. That is where we should be building.
Read the original at CryptoSlate →