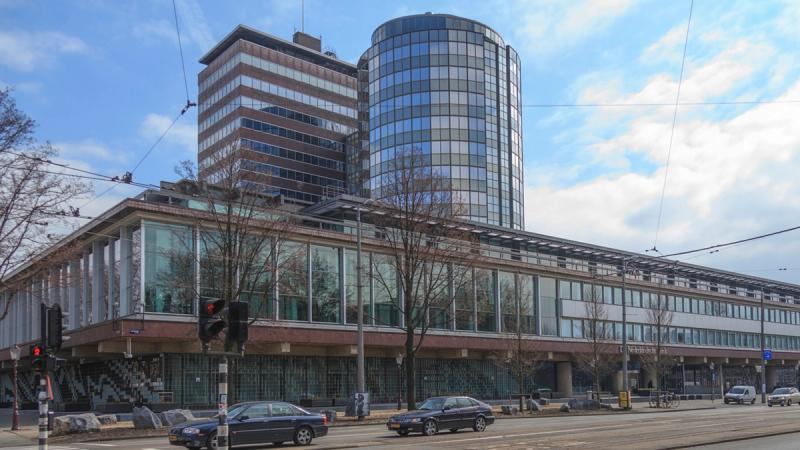
The Dutch central bank just handed a permission slip to Qivalis, granting them an Electronic Money Institution license. On the surface, it is another MiCA headline. But look at who is writing the checks: BBVA, BNP Paribas, and ING. This is not a group of teenagers in a garage; this is the old guard building their own front door to the blockchain.
The Institutional Pivot to Euro Settlement
For years, crypto builders had to rely on stablecoins that lived in a legal gray area. We used tokens backed by offshore accounts and opaque audits because that was all we had. Qivalis represents the next phase. By securing this license under the Markets in Crypto-Assets regulation, they are positioning themselves as the compliant plumbing for euro-denominated transactions onchain.
This is not just about having another stablecoin. It is about settlement infrastructure. When major European banks back a project like this, they are looking for a way to move money across borders and through smart contracts without the friction of the traditional SWIFT system, while keeping the regulators happy.
Why Builders Should Pay Attention
If you are building in the DeFi or fintech space, the arrival of fully regulated, bank-backed euro tokens changes your risk profile. The days of worrying if your stablecoin provider will get shut down by the SEC or a European equivalent are starting to fade for those who choose these regulated paths.
Working with an EMI-licensed entity means you are operating within a framework that the legacy financial system understands. This makes it significantly easier to bridge the gap between a decentralized application and a traditional corporate bank account. For founders, this means fewer headaches during off-ramping and more credibility when pitching to enterprise clients.
The MiCA Effect
Europe is currently setting the pace for regulatory clarity. While the United States remains mired in a game of enforcement-by-whack-a-mole, the EU has provided a rulebook. Qivalis is one of the first major movers to leverage this new clarity to create a specific type of infrastructure: the euro token as a settlement layer.
We are seeing a trend where the "electronic money" designation is becoming the gold standard for onchain assets. It provides a level of consumer protection and reserve requirements that simply did not exist in the early days of Tether or USDC. For the builder, this translates to a more stable foundation, but it also means more compliance overhead.
What This Means for the Future of Payments
The involvement of ING and BNP Paribas suggests that these banks are tired of being observers. They want to own the pipes. If Qivalis succeeds in becoming the primary onchain euro settlement layer, it could centralize a lot of the liquidity that is currently scattered across various bridge protocols and wrapped assets.
The real innovation here isn't the token itself, but the regulatory bridge it builds. Banks aren't trying to replace crypto; they're trying to absorb the parts that work and discard the parts they can't control.
Challenges and Skepticism
As a founder, I always look at these institutional plays with a bit of a side-eye. The benefit is stability and legality. The drawback is censorship and centralization. A MiCA-compliant euro token will likely have blacklisting capabilities built into the smart contract level. It will require rigorous KYC for anyone interacting with the core minting and burning mechanisms.
This is the trade-off we are making. We get the liquidity of the global banking system, but we lose the permissionless nature that defined the early crypto ethos. For most commercial applications, this is a trade they are willing to make.
Strategic Takeaways for Crypto Founders
- Focus on Compliance Early: If your project touches the European market, you can no longer ignore MiCA. The Qivalis license shows that the regulator is active and ready to approve those who follow the rules.
- Enterprise Integration: Start thinking about how your stack interacts with regulated euro tokens. The liquidity will flow where the banks feel safe.
- Diversify Settlement: Don't rely solely on USD-backed assets. The emergence of credible Euro tokens provides a necessary hedge against US regulatory volatility.
The Bottom Line
Qivalis getting the nod from the Dutch central bank is a signal that the sandbox phase of crypto in Europe is ending. The adults—or at least the people with the biggest balance sheets—have entered the room. They are building the infrastructure that will allow traditional finance to finally migrate onchain without losing their shirts or their licenses. For builders, it is time to decide if you are going to fight the tide or build the tools that help these giants move.
Read the original at CoinDesk →