The Shadow Banking Illusion
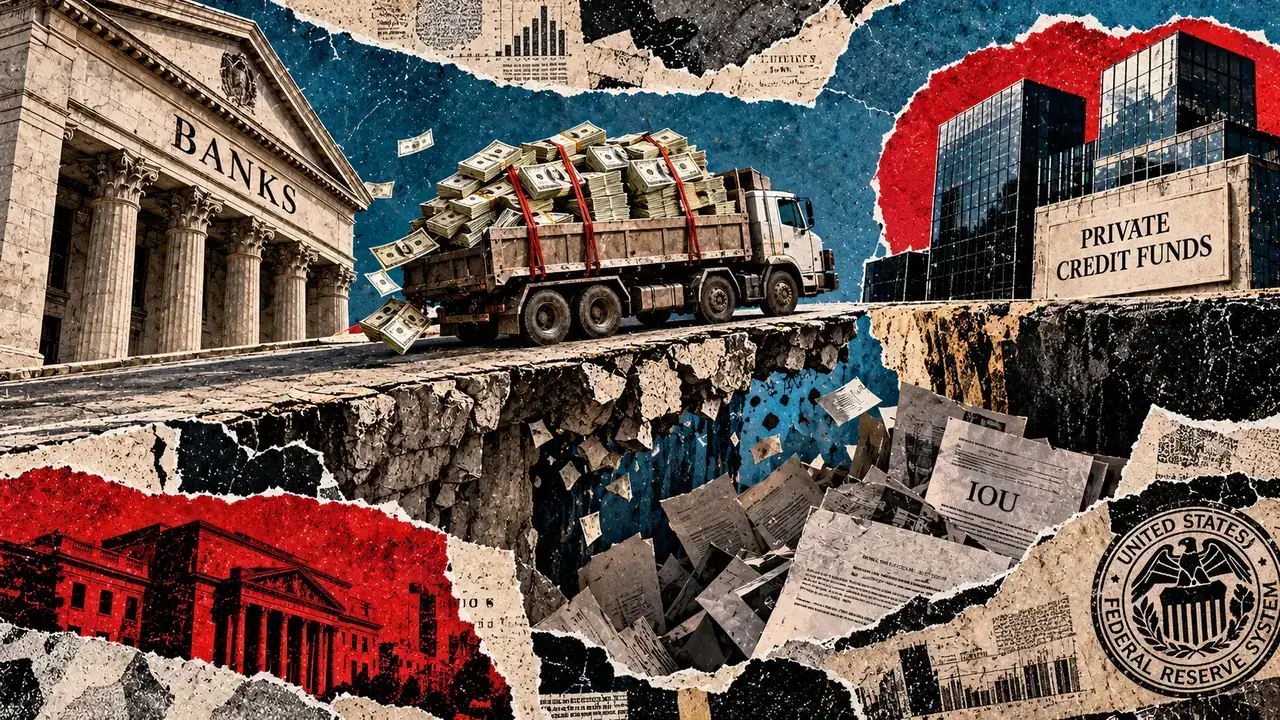
For the last decade, private credit has been the darling of the institutional world. It was marketed as the safer, more adult alternative to the wild volatility of crypto and the stagnation of traditional public bonds. But as the tide goes out, we are starting to see exactly who has been swimming without a suit. Right now, traditional banks are sitting on roughly $349 billion in loans issued to private credit funds. The problem? Those funds might be reporting income that doesn't actually exist in the form of cold, hard cash.
This isn't a secret conspiracy; it is a feature of the contracts. Many of these private loans include provisions for Payment-in-Kind (PIK) interest. Instead of the borrower sending a wire transfer every month to cover their interest, they simply add that interest to the principal balance of the loan. On the fund's balance sheet, this looks like a gain. They mark it down as income, their internal rate of return looks healthy, and investors stay happy. But in reality, no money moved. The fund is essentially pinky-promising that they will get paid later.
The Leverage Mismatch
If these private credit funds were just playing with their own money, this would be a niche problem for wealthy family offices. But they aren't. To juice their returns, these funds borrow heavily from traditional banks like JPMorgan, Goldman Sachs, and Citi. This creates a dangerous structural mismatch. The banks expect their interest and principal payments in cash, on a strict schedule. Meanwhile, the private credit funds are allowing their own borrowers to defer payments indefinitely through PIK arrangements.
As a founder, you know that paper profits don't pay the bills. You can have the most impressive GAAP accounting in the world, but if your bank account is empty when payroll hits, you are out of business. The private credit market is currently testing the limits of this reality. We are looking at a $349 billion bridge where one end is anchored in the rigid world of traditional banking and the other end is floating in the subjective world of private valuations and deferred interest.
Why This Matters for Builders
You might be wondering why a crypto or AI founder should care about the plumbing of institutional debt markets. The answer is simple: liquidity is global. When the private credit market catches a cold, the venture capital and private equity markets get pneumonia. If these funds start facing margin calls from the banks because their cash flow doesn't match their reported income, they will stop lending. They will stop participating in late-stage rounds. They will start selling assets at a discount to raise cash.
For those building in the decentralized finance (DeFi) space, this is a massive validation of on-chain transparency. In a DeFi protocol, you can't really hide a lack of cash flow behind a PIK provision unless the smart contract specifically allows for it, and even then, every participant can see the lack of collateral movement in real-time. The traditional financial world is still operating on quarterly reports and trusted valuations, which allows these $349 billion holes to grow in the dark.
The Ghost of 2008
This feels eerily similar to the credit structures that led to the 2008 financial crisis, though the labels have changed. Back then, it was subprime mortgages wrapped in layers of derivatives. Today, it is mid-market corporate debt wrapped in private credit funds that are leveraged by global banks. The common thread is the obfuscation of risk. When a borrower can't pay their interest and the lender says, "don't worry, just pay us more later," that isn't a sign of a healthy economy. It is a sign of a borrower in distress and a lender who is too afraid to take a mark-down.
If I am a founder looking at the next 18 to 24 months, I am assuming that the cost of capital is going to remain high and that the availability of that capital is going to tighten. The "easy money" that flowed from banks into private credit and then into the broader tech ecosystem is hitting a wall. The banks are going to want their $349 billion back, and they are going to want it in cash, not in "accrued interest" tokens.
The Takeaway for the Ecosystem
We are entering a period where honesty in accounting will become a competitive advantage. The funds and startups that can demonstrate real cash flow and sustainable margins will survive the coming liquidity crunch. The ones relying on accounting gimmicks and deferred liabilities will be exposed as the banks tighten their belts.
- Transparency is the only hedge: On-chain builders should lean into the fact that their solvency is provable.
- Cash is king: Paper gains mean nothing in a high-interest-rate environment where banks are hunting for liquidity.
- Watch the banks: The $349 billion owed by private credit funds is a ticking clock for the next round of banking volatility.
The gap between reported income and actual cash flow is where financial crises are born. When $349 billion is trapped in that gap, everyone should be paying attention.
Read the original at CryptoSlate →